
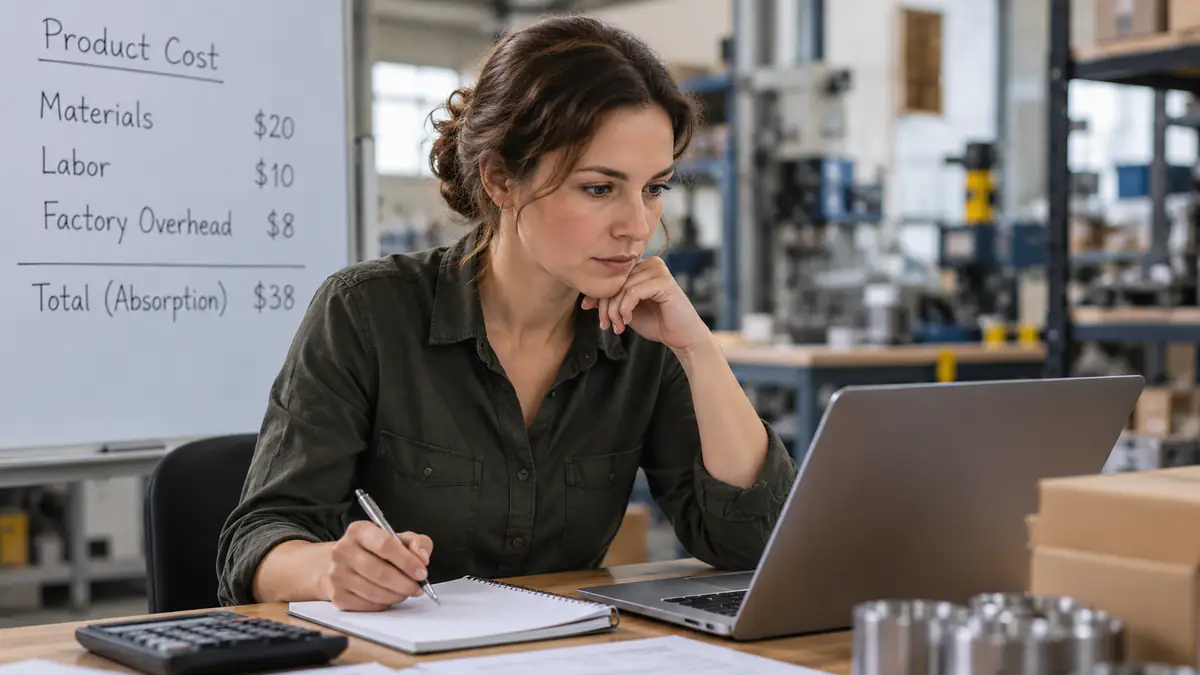
A product can be selling well and still be harder to price than it looks.
The direct costs may be easy to see. Materials cost $20, labor adds another $10, and the selling price leaves what appears to be a healthy margin. But if the business also pays for production space, machinery, and other fixed manufacturing resources, that simple calculation leaves part of the picture out.
Absorption costing can help when fixed production costs materially affect a product’s economics. It assigns both variable and fixed production costs to products, giving businesses another reference point when reviewing prices. It should not, however, determine the selling price on its own. Demand, competition, capacity, and the type of pricing decision still matter.
For retailers that buy finished goods rather than manufacture them, formal absorption costing may have a smaller role. In those cases, accurate purchase and landed costs can be more useful for understanding product margins.
Key takeaways
- Absorption costing includes fixed production overhead in product cost, which can reveal costs that a variable-cost calculation leaves outside the unit.
- It is most relevant when a business manufactures or converts goods, and those products use meaningful shared production resources.
- An absorbed cost is a reference for pricing, not a guaranteed market price. Customers and competitors can support a price that is higher or lower.
- Retailers buying finished products may need a different cost view, with greater attention to acquisition, landed costs, and channel economics.
What is absorption costing?
Absorption costing is a method that assigns both variable manufacturing costs and a share of fixed production overhead to the products a business makes.
At a basic level, the cost assigned to a product can include:
Direct materials + direct labor + variable production overhead + allocated fixed production overhead = absorption cost
Fixed production overhead might include costs such as factory rent or depreciation on production equipment. The business allocates those shared costs across the goods produced using an appropriate basis.
This makes absorption costing different from variable costing, which keeps fixed production overhead outside the unit product cost.
Accounting standards also use this principle for inventory valuation. Under IAS 2, costs of conversion include systematic allocations of fixed and variable production overhead. Fixed production overhead is allocated based on normal production capacity rather than simply dividing overhead by unusually low output.
However, absorption costing should not be confused with the complete commercial cost of selling a product. Selling expenses and some administrative costs are not part of the absorbed production cost under inventory accounting rules.
That distinction becomes important when using absorption costing for pricing.
How does absorption costing affect product pricing?
Absorption costing gives a business a broader production cost figure to consider before setting or reviewing a price.
Suppose a brand manufactures a product with $30 of variable production cost per unit. Once the business assigns $10 of fixed manufacturing overhead, the absorption cost becomes $40.
If management uses a 25% markup on that figure, the resulting price would be $50.
The calculation is straightforward. The decision is not.
Customers may only be willing to pay $45. Strong demand or brand value could support $65. A competing product could sell for $48. None of those market conditions changes because the accounting system calculated a $40 absorbed cost.
This is one limitation of cost-based pricing. A price calculated from cost may still fail if customers will not pay it or competitors offer a lower alternative. Cost-plus pricing can also produce a price below what customers would have accepted.
Absorption costing is therefore better used to inform a pricing decision than to make that decision automatically.
When should you use absorption costing in product pricing?
When your products use meaningful fixed production resources
Absorption costing is most directly relevant to businesses that manufacture, assemble or otherwise convert goods.
A company with production facilities incurs costs even when those costs cannot be traced neatly to one item. Assigning an appropriate share of production overhead can give management a better view of the resources associated with each product.
This matters when direct costs alone make a product appear more profitable than it does after production overhead is considered.
For a retailer purchasing finished merchandise from a supplier, the situation is different. The supplier may have fixed manufacturing overhead, but the retailer does not need to recreate the supplier’s production cost model. Its own product economics begin with what it pays to acquire the stock and the other relevant costs it incurs.
When reviewing whether a product supports the resources it uses
A price can produce a positive contribution after variable costs and still leave questions about the economics of the product over time.
If several products share a production facility, management needs some way to understand how those resources are being used. Absorption costing can provide one view of that relationship.
The result still requires judgment. An allocated share of factory rent is not the same as a cash payment caused by selling one additional unit. It can, however, show whether a product portfolio generates enough revenue to support the production resources behind it.
This is where absorption costing becomes more useful for planning over multiple periods than for judging one isolated transaction.
When production capacity is part of the pricing decision
Capacity changes how useful allocated costs can be.
Research into service pricing has found a stronger relationship between allocated costs and prices when capacity utilization is high. When resources are scarce, using them for one product or customer can carry an opportunity cost because that capacity cannot be used elsewhere.
The study does not establish a universal rule for retail businesses. A retailer’s constraint may be very different from a hospital’s. It could be manufacturing capacity, supplier availability or another resource.
The principle is still useful: before relying on an allocated cost for pricing, ask whether the product is actually consuming a resource that is difficult to replace or expand.
When can absorption costing lead to a poor pricing decision?
When the decision concerns an incremental sale and capacity is available
Imagine a manufacturer has unused capacity and receives an additional order. Factory rent will be paid whether the company accepts the order or not.
Rejecting the order simply because its price does not recover an allocated share of that rent could therefore overlook a profitable opportunity.
For decisions like these, relevant or marginal cost information may be more useful. Relevant costs focus on future cash flows caused by accepting a product or contract, rather than costs that will be incurred regardless of the decision.
This does not make fixed costs unimportant to the business. It means their relevance changes depending on the question being asked.
When the market will not support the calculated price
Absorption costing looks inward at the company’s cost structure. Customers do not price products from the company’s cost ledger.
A business can calculate its overhead allocation correctly and still arrive at a price that is too high for the market. It can also underestimate the value customers place on a product and charge less than buyers would have accepted.
Cost information should therefore be checked against actual market conditions before a price changes.
When the overhead allocation does not reflect resource use
An absorption cost depends partly on how shared production overhead is assigned.
If every product is allocated overhead based on labor hours, but some products require far more machine time, quality checks, or production support than others, the allocation may distort their apparent economics.
That does not make overhead irrelevant. It means managers should question the allocation method before making pricing or portfolio decisions based on the resulting unit cost.
When low output makes the unit cost look artificially high
Fixed production costs do not disappear when output falls. Dividing the same fixed costs among fewer units can therefore produce a much higher cost per item.
For accounting purposes, IAS 2 addresses this by allocating fixed production overhead using normal capacity and recognizing unallocated overhead as an expense when production is abnormally low.
The same logic is useful when reviewing internal pricing calculations. Raising a product’s price simply because a single weak production period shifted more overhead onto every unit could make the demand problem worse.
Absorption costing vs. variable costing for pricing
Neither method answers every pricing question.
|
Pricing question |
Absorption costing |
Variable or relevant costing |
| What enters the product cost? | Variable production costs plus allocated fixed production overhead | Costs that change with output, or future cash flows relevant to the specific decision |
| What can it help reveal? | How products relate to the wider production cost base | What an extra sale, order or contract contributes after the costs it causes |
| Where can it help most? | Product economics over a longer period, especially where production resources matter | Temporary pricing decisions, spare-capacity decisions and incremental orders |
| What is the main limitation? | Allocated overhead may not reflect the economic cost of one additional sale | Looking only at incremental costs can understate the resources the business needs to fund over time |
The choice should follow the decision rather than the other way around.
A team considering whether to accept an extra order from available capacity needs different information from a team deciding whether an entire product line deserves continued investment.
How to use absorption costing in a practical pricing strategy
Start with the type of business
First, establish whether absorption costing is actually relevant.
If you manufacture or assemble products, fixed production overhead may belong in the analysis. If you purchase finished stock for resale, purchase and landed costs may provide a more meaningful starting point.
Landed cost can include expenses associated with bringing inventory to its destination beyond the supplier price. Brightpearl, for example, supports landed-cost tracking for costs such as freight, duties, and insurance.
Match the cost method to the decision
A product-line review, a one-time order, and a temporary promotion should not automatically use the same cost figure.
For a decision about ongoing production economics, absorbed cost can provide useful context. For a one-off sale from idle capacity, relevant costs may deserve more weight.
Defining the question first reduces the risk of using a familiar accounting number simply because it is readily available.
Check how fixed overhead has been allocated
Before relying on an absorbed unit cost, understand what sits inside it.
Ask whether the allocation basis reflects how products actually consume production resources and whether the calculation uses a reasonable production level. A large change in absorbed unit cost should have an operational explanation, not just a spreadsheet explanation.
Test the result against the market
Once the business understands its cost position, compare the proposed price with customer behavior and competitive conditions.
If the market price is consistently below the amount needed to make the product economically attractive, the answer may not be another markup calculation. The business may need to examine production cost, product design, or whether the product still belongs in the range.
If customers would comfortably pay more than a cost-based calculation suggests, using absorbed cost as the final pricing answer can also leave money on the table.
Look beyond one cost number
Retail pricing depends on more than manufacturing cost.
Teams may also need visibility into purchase costs, landed costs, inventory value, and actual margins across channels. Keeping those figures connected with retail accounting data makes it easier to see whether a change in product cost is flowing through to profitability rather than working from separate spreadsheets or outdated records.
Connect product cost data with retail operations
Pricing becomes harder when inventory, purchasing, and financial information sit in different systems.
Brightpearl’s Retail Operating System connects order management with inventory management, purchasing, and accounting data within the same retail operations environment. Its inventory and accounting capabilities include FIFO inventory valuation, automatic product cost calculations, and landed-cost reporting. Teams can also view financial and product performance data as transactions move through the business.
For retailers, that visibility can help finance and operations teams understand how changes in purchasing or inventory costs affect product margins without treating one costing method as the answer to every pricing question.
Book a demo to see how Brightpearl can connect inventory, purchasing, and financial data across your retail operations.
FAQs about absorption costing and pricing
Is absorption costing the same as activity-based costing?
No. Both methods can assign overhead to products, but they do so differently.
Traditional absorption costing commonly assigns production overhead using measures such as labor or machine hours. Activity-based costing identifies activities that consume resources and uses related cost drivers to assign overhead. ABC can provide a different view when products place very different demands on shared activities.
Can absorption costing change reported profit when inventory builds up?
Yes. Under absorption costing, fixed production overhead forms part of the cost assigned to inventory. If production exceeds sales, some of that fixed overhead remains in unsold inventory rather than being recognized immediately in cost of goods sold.
The accounting treatment means reported profit can differ from the result under variable costing when inventory levels change. Managers should not increase production simply to spread fixed overhead across more units, as this can create excess inventory without improving underlying demand.
How often should a business review its overhead absorption rates?
There is no single review schedule that fits every business.
A company should revisit its assumptions when production capacity, processes or cost structures change enough to make the existing allocation less representative. Large unexplained movements in product cost can also signal that the allocation basis deserves another look.
Accounting guidance, such as IAS 2, uses normal production capacity when allocating fixed production overhead, which helps prevent temporary low output from distorting inventory cost.


